
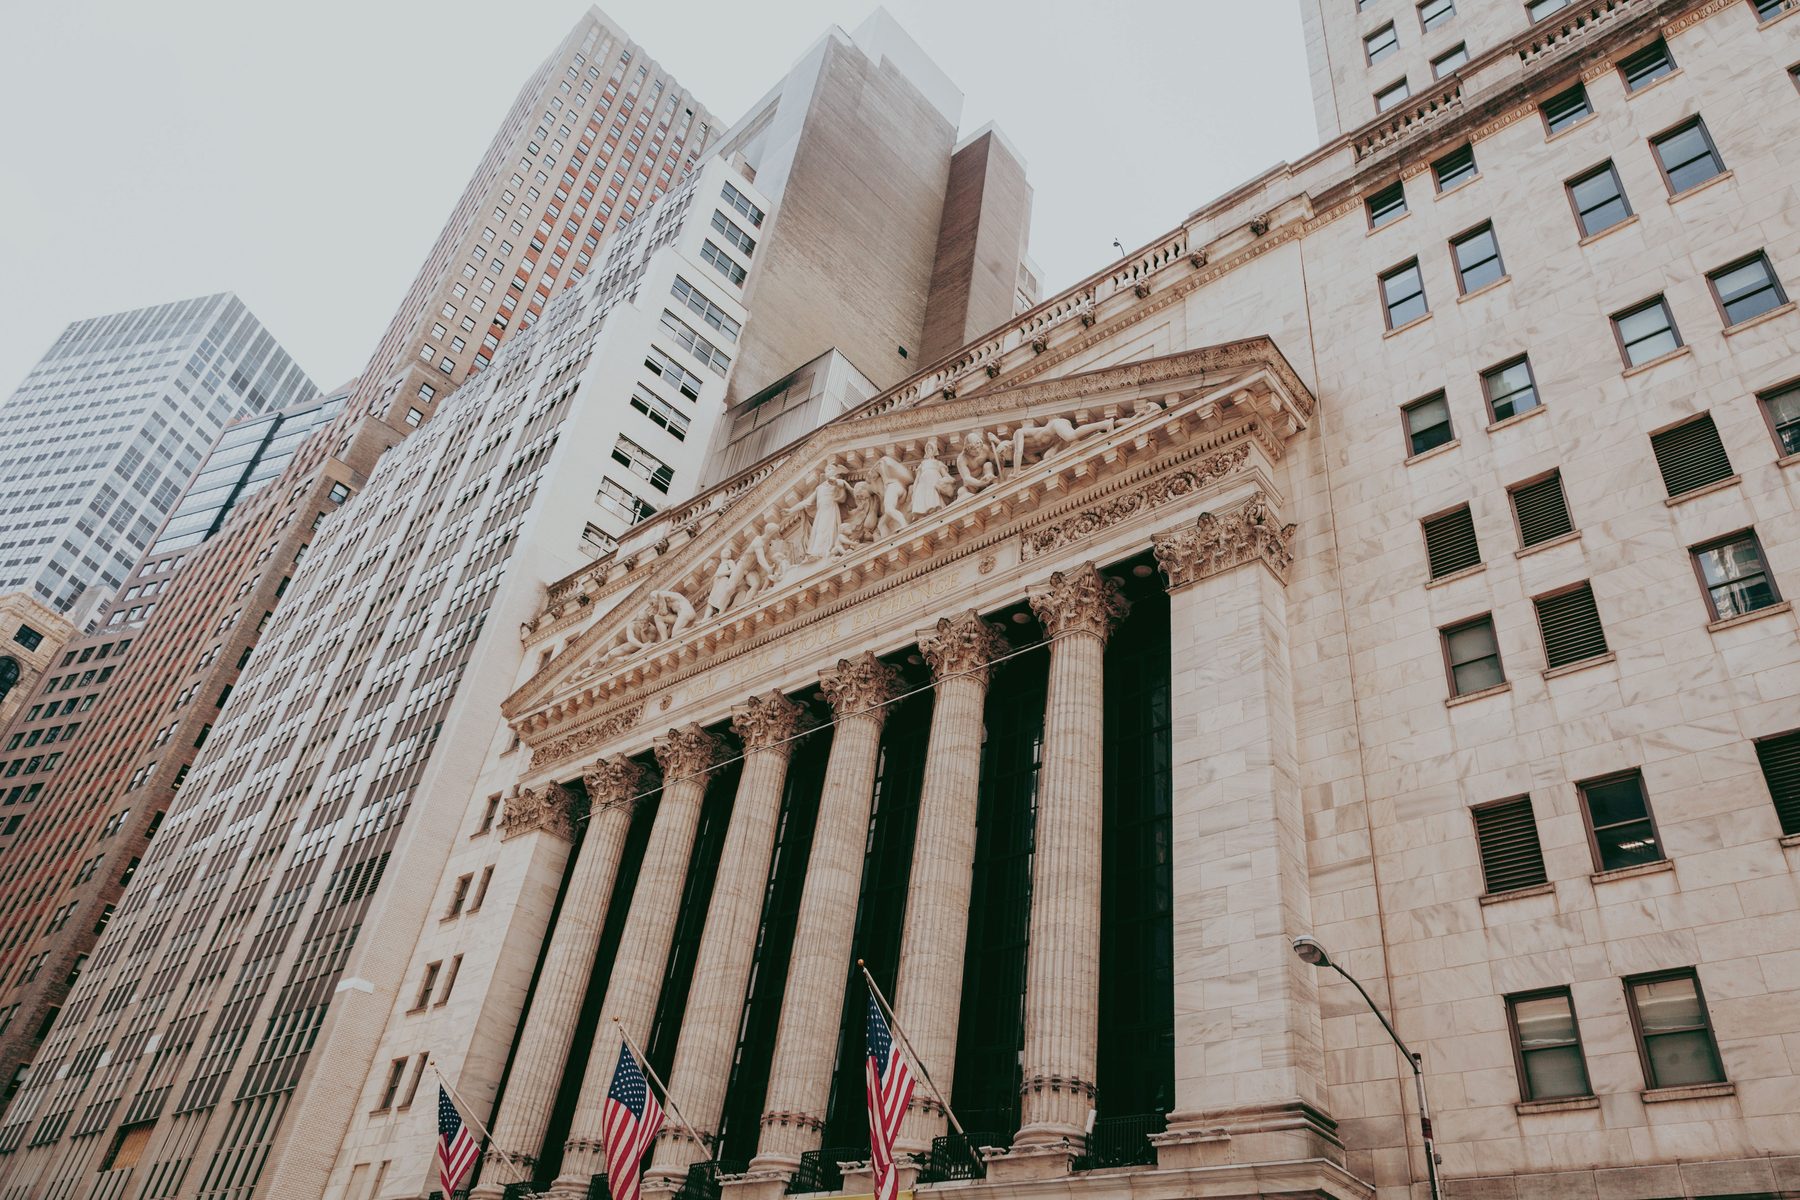
The New York Stock Exchange recently announced a surprise development. The 234-year-old exchange — the largest in the world — is creating a new platform for trading tokenised securities, signaling its embrace of the technology pioneered by bitcoin and now used to create digital representations of stocks, bonds, real estate, and other assets.
What drew even more attention, however, was not tokenisation itself, but the operating hours. Pending regulatory approval, the new exchange is expected to run 24 hours a day, 365 days a year. No closing bell. No market holidays. Always on.
That decision reflects a broader shift already underway. As financial assets become increasingly digital, the assumption that markets must pause — overnight, on weekends, or for holidays — starts to feel less like a necessity and more like a legacy of an earlier era.
Tokenisation accelerates this shift. By recording ownership and transactions on a shared digital ledger, it allows assets to move and settle almost instantly. In principle, nearly anything — from corporate debt to real estate — can be exchanged, verified, and cleared in real time, anytime.
Like the ETF before it, tokenisation represents another step in the modernisation of market infrastructure. For individual investors, it may expand access through fractional ownership. For institutional investors, its impact is more immediate: it compresses time.
Traditional financial markets still reflect their paper-era roots. Even in today’s high-speed trading environment, settlement often occurs on a delayed schedule — T+2, T+1, or ‘same day’ in name only. Those delays are one reason markets have historically accepted downtime. Waiting has always been part of the system.
When assets and ownership change hands simultaneously, delays are no longer merely an inconvenience. If settlement is instantaneous, liquidity must be too. That tension is what 24/7 markets make impossible to ignore.
And it is where the cash leg begins to matter.
The dragging cash leg
Money market funds have long played a central role in institutional finance. Structurally, they are managed securities like any mutual fund. Practically, because they invest in high-quality, short-dated government and bank-issued securities, they function as yield-bearing cash.
That yield — modest but steady — has made money market funds an essential tool for trading desks and asset managers managing collateral, repo, and securities lending. Despite their role as cash substitutes, MMFs still settle like managed funds, mirroring the operating hours and settlement rhythms of the underlying assets they hold. Redemption typically occurs on a T+1 basis. Even when ‘T+0’ is advertised during market hours, accessing cash can take several hours.
Off-chain money movement takes time. On-chain doesn’t.
Fragmented ledgers, T+2 or 3 reconciliation
Off-chain money movement takes time
Shared ledger, Intraday 24/7
On-chain money programmability
There are risks associated with blockchain technology. In addition, price discovery and intraday trading and settlement of a token fund may not be possible under certain conditions.
In traditional markets, this lag has been manageable. Institutions often redeem MMF positions early to ensure liquidity is fully available when needed, accepting periods of idle cash as the cost of coordinating across counterparties, clearing systems, and jurisdictions. This is simply how a T+ world has functioned.
In tokenised markets, that option disappears.
In an instant, 24/7 environment, the cash leg has nowhere to hide. Approximated liquidity is not sufficient. A few hours of uncertainty can be enough to disrupt execution, collateral management, or risk controls. What used to be tolerable slack turns into a break in the system.
Anyone operating on-chain runs into this almost immediately.
Right from the start
Fidelity International began exploring tokenised liquidity in late 2022, initially pursuing what was then the prevailing industry approach: creating a digital representation of an existing money market fund and placing that ‘twin’ on chain.
By mid-2023, a prototype was ready for testing. At the time — as today — that meant working closely with crypto-native trading firms and market participants.
The feedback was unambiguous.
We heard a lot of negative. The people we met with appreciated that the fund spoke the same language as other on-chain assets. But behind the scenes, it was still really just a representation of its off-chain twin. Settlement was still T+0 or T+1. That wasn’t good enough. They needed instant settlement, 24/7. They were very clear about that.
The response highlighted the fundamental difficulty of bridging DeFi and TradFi workflows. Stablecoins had become widely used as collateral precisely because they settle instantly and continuously, even though their most common, liquid forms yield nothing and do not provide daily disclosure of underlying holdings. Speed and certainty mattered more.
At the time, regulatory uncertainty reinforced a range of interim solutions. Many tokenised funds simply gestured to immediate availability. Where that became more of a sticking point with users, some providers relied on secondary market makers or other external dependencies to plug the gap.
These approaches worked — up to a point.
A regulatory inflection arrived in 2025, when new frameworks explicitly allowed tokenised liquidity funds to be built natively on-chain. Institutions with existing ‘digital twin’ models rushed to adapt, layering additional workarounds and promises onto structures originally designed for a lower settlement bar.
Fidelity International was in a different position. Our early prototype had always been experimental. As a non-US-based firm with operations across Europe and Asia, we also had the flexibility to select the regulatory framework best suited to a fully digital end state.
The conclusion was clear: if on-chain markets required atomic settlement, the cash supporting them had to be built the same way — native, continuous, and 24/7, even if portions of the broader financial system remained tied to legacy settlement infrastructure.
When ‘24/7’ isn’t quite what it seems
Today, several liquidity solutions describe themselves as always available. In practice, that availability is largely a matter of client discretion and is achieved only through secondary-market activity on broker-dealer desks. Even in rare cases where a fund has been built on-chain, OTC workarounds and permissions granted by stablecoin platforms must bridge the after-hours when liquidity mechanisms supporting the underlying Treasury, repo, and bank-note markets are closed. These arrangements can work smoothly, but they introduce additional layers of dependency and costs.
Different paths. Different outcomes.


It’s actually cheaper to operate a digital twin than an on-chain fund. After all, an on-chain fund needs to arrange immediate liquidity for underlying securities that do not, themselves, yet settle on-chain. However, once a fund moves on-chain or tries to act as if it has, the more workarounds it requires, the more those extra basis points can add up.
More importantly, reliance on secondary liquidity and external relationships means availability is not purely a function of the fund itself. It can vary with market conditions, counterparties, or time of day. Settlement may feel instant, but it is not ‘atomic’ in the strict sense.
For institutions operating on-chain, these distinctions matter.
What FILQ is — and what it’s built to do
FILQ was designed to eliminate those trade-offs. Built natively on-chain, it supports continuous blockchain-native subscriptions and redemptions, while also allowing institutions the flexibility to manage liquidity without relying on secondary-market intermediaries or external stablecoin bridges. During out-of-market hours, a blockchain-enabled liquidity facility with J.P. Morgan is available to keep subscriptions and redemptions flowing for a small fee measured in a few basis points for that day’s access. In sum, FILQ represents a new category of liquidity instrument. It borrows the risk profile and yield characteristics of money market funds but is qualitatively different because of where and how it was built and what it allows shareholders to do.
Comparison: FILQ vs. other liquidity options
| Regulated Tokenised Liquidity (FILQ) | Public Stablecoins | Traditional money funds | |
|---|---|---|---|
| Leverages blockchain technology | ✓ | ✓ | — |
| Close to instant settlement1 | ✓ | ✓ | — |
| Regulated product2 | ✓ | ? | ✓ |
| Earns yield that is distributed daily | ✓ | — | ✓ |
| Historically stable valuation | ✓ | ? | ✓ |
Source: Fidelity International, as of 11 May 2026. 1Settlement occurs on a confirmed-funds basis with near-immediate execution during market hours and under normal market conditions, as soon as technically practicable, using the speed of the relevant distributed ledger technology. Constant NAV is used (in a normal market environment). However, Market Price NAV will be calculated alongside Constant NAV and will be used when the difference between the situation defined as ‘Stressed Market Environment’. The Fund will generally accept subscription and redemption orders on a continuous 24/7 basis; however, orders may not always be processed immediately and may be subject to liquidity and operational constraints, including scheduled maintenance periods (Saturdays between 3:00 p.m. and 6:00 p.m. Eastern Standard). Please refer to the prospectus for more details. The fund is registered with Cayman Islands Monetary Authority.
2The Fund is an exempted company registered as a segregated portfolio company under the laws of the Cayman Islands. The Fund is regulated by the Cayman Islands Monetary Authority (CIMA) under the Mutual Funds Act.
FILQ has launched on the Ethereum blockchain, making cash continuously available, while still earning yield. It is built so that as more assets move on-chain, including T-bills and other short-dated securities generating that yield, it can evolve to become even more frictionless from day one.
For institutions operating in tokenised markets, that combination — credibility, composability, and yield — is the point. FILQ isn’t a yield strategy or a thought experiment. It’s infrastructure designed to behave like on-chain cash, because that’s what users increasingly demand.
As markets become always-on, the liquidity is ready.
Market participants should take all the downtime they earn.
Cash should earn without a break.
Important information
Please refer to the Prospectus of the Fund before making any final investment decisions.
The investment which is promoted concerns the acquisition of shares in a fund and not in any given underlying asset owned by the fund. Complete information on risks can be found in the Prospectus.
The Fund seeks to invest in a diversified range of short-term instruments with the aim of maintaining capital value and liquidity whilst producing a return to the investor in line with money market rates. The Fund may invest in: a range of high-quality money market instruments (government and non-government), securitisations and ABCP and money market funds; and deposits, provided they are payable in USD.
Credit Risk: In an extreme case, a debt investment could go into default, meaning its issuer could become unable to make timely payments to the fund.
24/7 Dealing and Liquidity Risks: The Fund will generally accept subscription and redemption orders on a continuous 24/7 basis; however, orders may not always be processed immediately and may be subject to liquidity and operational constraints, including scheduled maintenance periods.
Investments in the Fund are subject to charges and expenses. Charges and expenses reduce the potential growth of your investment. This means you could get back less than you paid in. Please note that not all costs are presented, further information on costs can be found in the Prospectus.
Put cash to work 24/7
Access institutional-grade liquidity on-chain, designed for digital markets.